Before They Can Walk, They Can Invest

Richard Shupick
How Trump Accounts Could Give a Generation an Earlier Start
Most parents spend the months before a child arrives preparing for the obvious expenses. There is the crib, the stroller, the mountain of diapers, and the car seat that somehow requires both an instruction manual and an advanced engineering degree to install. An investment account for the baby usually does not make the shopping list.
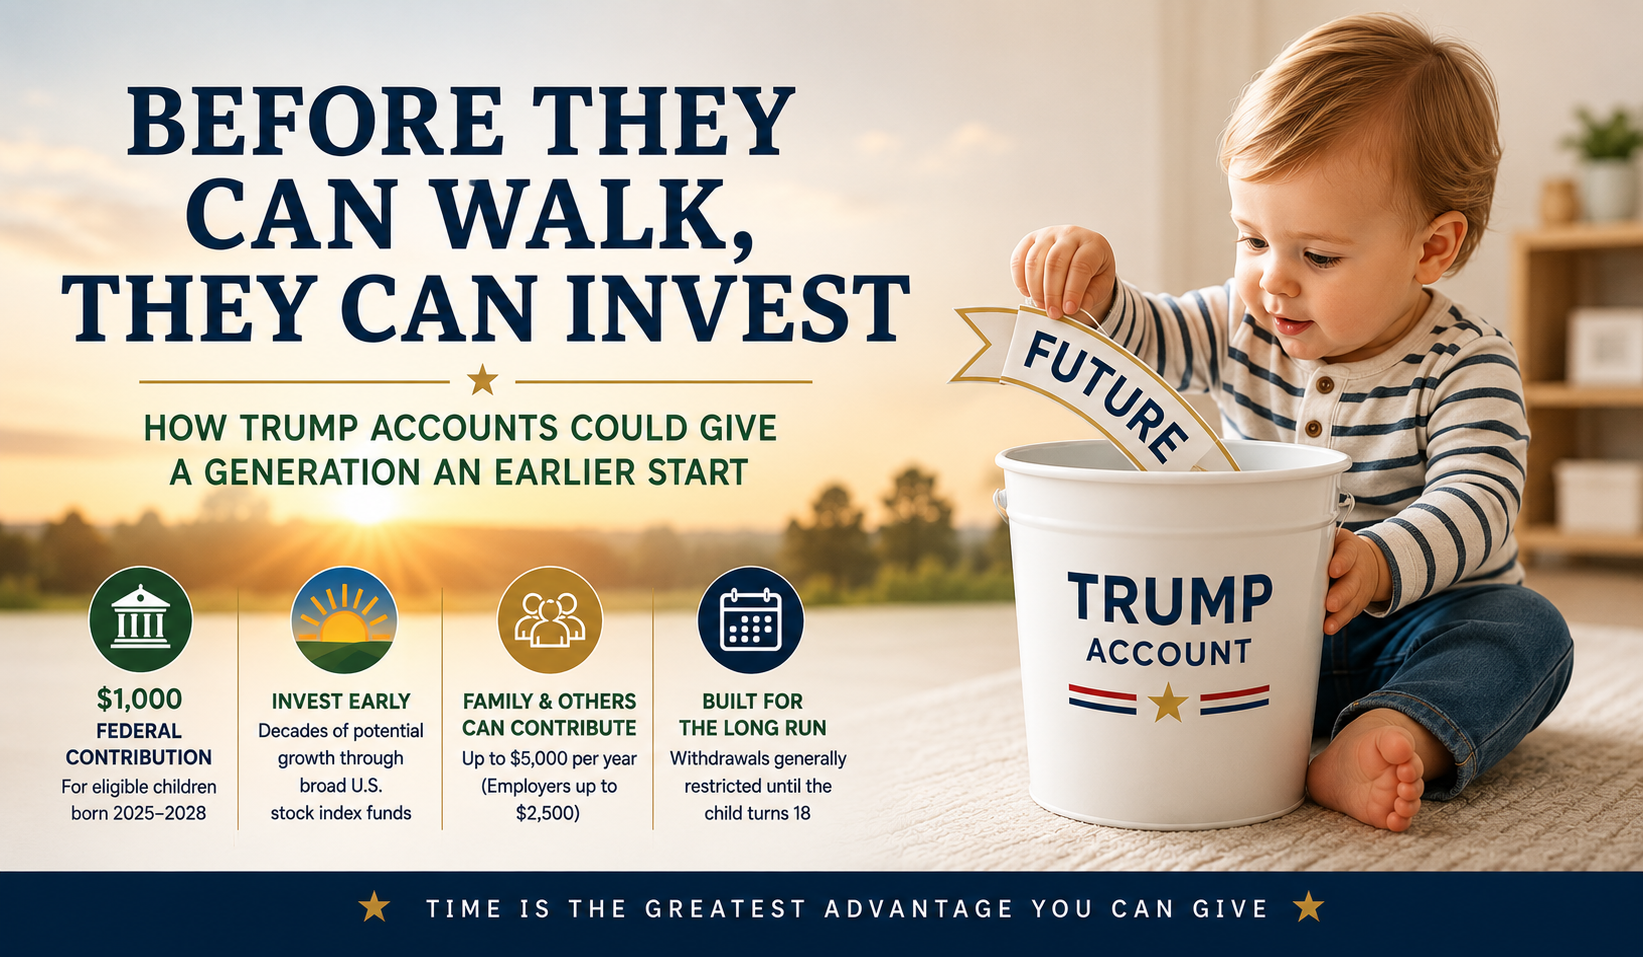
That may be changing. A new type of tax advantaged investment account, commonly called a Trump Account, is now available for eligible children. Children born from January 1, 2025, through December 31, 2028, may qualify for a one time $1,000 federal contribution, provided the required election is made and the child meets the citizenship and Social Security number requirements.
The account is not automatically opened simply because a child qualifies. A parent, guardian, or another authorized person must establish the account and request the federal contribution. For families who take that step, a child could become an investor before learning to walk, talk, or sleep through the night.
A $1,000 Beginning, Not a Complete Financial Plan
The federal contribution is best understood as a starting point rather than a complete financial solution. The government provides a one time $1,000 pilot contribution for an eligible child, but there is no required family match and no automatic second $1,000 contribution. Parents and other contributors may choose to add money, subject to the account’s annual contribution limit.
Children do not necessarily need to be born during the four year pilot period to have a Trump Account. An account may generally be established for an eligible child who has not reached age 18 before the end of the year in which the election is made and who has a valid Social Security number. However, the federal $1,000 contribution is limited to qualifying United States citizens born from 2025 through 2028.
Current IRS guidance does not describe the government contribution as being reduced or eliminated according to household income. Eligibility instead centers on the child’s birth date, citizenship, Social Security number, and completion of the required election. Families should review the actual requirements rather than assume they earn too much to participate.
The Account Is Designed to Keep Investing Simple
Trump Accounts are not intended to become miniature trading platforms where parents speculate on individual companies for their toddlers. During the child’s growth period, the money must be invested in qualifying funds that track broad indexes of primarily United States stocks. The objective is diversified market exposure with expenses that remain within the program’s limits.
The Treasury Department has announced the initial investment lineup. At launch, contributions are invested by default in the State Street SPDR Portfolio S&P 500 ETF (SPYM). This fund tracks the S&P 500 Index and provides exposure to many of the largest publicly traded companies in the United States.
Treasury has also selected four additional exchange traded funds for the program. As the investment election system becomes available, parents and guardians are expected to have the ability to choose among:
- iShares Core S&P 500 ETF (IVV)
- Vanguard Total Stock Market ETF (VTI)
- State Street SPDR Portfolio S&P 1500 Composite Stock Market ETF (SPTM)
- iShares Core S&P Total U.S. Stock Market ETF (ITOT)
Until those additional investment elections become available, contributions remain invested in the default fund, SPYM. Families should consult the official program website for current information about when allocation choices can be made and how those elections will be processed.
A limited menu may feel unusual to investors accustomed to having hundreds of choices. Yet fewer options could help families avoid unnecessary complexity, overlapping funds, and the temptation to chase whichever investment theme recently appeared on the evening news. Sometimes simplicity makes it easier to remain focused on the original goal.
The Real Advantage Is Time
The initial $1,000 may not sound transformational. It could disappear quickly if spent on diapers, formula, or the growing collection of baby equipment occupying every corner of the house. Once invested, however, that same amount gains something an adult approaching retirement can never purchase: decades of potential growth.
Assume, purely for illustration, that the $1,000 earns an average annual return of 7 percent. By age 18, it could grow to approximately $3,380 without another contribution. If the family adds another $1,000 near the beginning, the resulting $2,000 could grow to approximately $6,760 by adulthood.
If that hypothetical $2,000 remained invested until age 65 and continued earning an average annual return of 7 percent, it could grow to approximately $162,500. This is not a prediction or guarantee, and actual investment results will vary. It simply demonstrates what may happen when a modest amount is given more than six decades to compound.
A newborn does not follow market forecasts, worry about interest rates, or move everything to cash after a difficult quarter. The child’s advantage is much simpler: the investment began early.
Small Contributions Can Reinforce a Valuable Habit
Parents, relatives, friends, employers, governments, and certain charitable organizations may contribute to these accounts. The combined amount is generally limited to $5,000 per year, with inflation adjustments scheduled to begin after 2027. Contributions from individuals generally are not deductible in the way certain traditional IRA contributions may be.
Employers may contribute up to $2,500 per year to an employee’s Trump Account or an account belonging to the employee’s dependent. That amount counts toward the overall annual limit, but a qualifying employer contribution generally is not included in the employee’s taxable income. This feature could eventually make Trump Accounts part of broader employee benefit discussions.
A family does not need to contribute the maximum for the account to have potential value. A grandparent might contribute on a birthday, or parents might add a modest amount each year and eventually show the child how the balance has changed. The account can then become a practical lesson in ownership, market fluctuations, and patience rather than simply another number on a statement.
Children are often told to save, but this account may allow them to see how investing works over time. That experience could be as meaningful as the eventual balance.
The Money Is Intended to Remain Invested Through Childhood
Trump Accounts generally restrict withdrawals during the child’s growth period. Funds ordinarily cannot be withdrawn before January 1 of the calendar year in which the child turns 18. This restriction supports the account’s long term purpose and reduces the likelihood that the balance will be gradually spent on unrelated childhood expenses.
After the growth period ends, the account generally becomes subject to rules similar to those governing a traditional IRA. Withdrawals may be taxable, and additional rules or penalties may apply depending on the account owner’s age and how the money is used. Families should not assume that a Trump Account offers the same withdrawal treatment as a 529 education plan or a Roth IRA.
That difference is why Trump Accounts should be viewed as one component of financial planning rather than a replacement for every existing account. A 529 plan may remain attractive when education is the primary goal, while a Roth IRA serves a different purpose and generally requires eligible earned income before contributions can be made.
How Families Can Get Started
Parents and other authorized individuals can make the election using IRS Form 4547. The election may be submitted through an IRS Individual Online Account, and the official Trump Accounts website provides information about establishing and managing an account. Families seeking the $1,000 federal contribution must specifically elect to receive it for an eligible child.
Contributions were not permitted before July 4, 2026, so the program is now moving from legislation into active implementation. Families should rely on the IRS, Treasury, and the official program website for current instructions because administrative procedures and investment election features may continue to develop.
Before making additional contributions, families should consider their broader financial priorities. Building an emergency reserve, managing debt, saving for education, and preparing for retirement may all compete for the same dollars. Giving a child an early investment account can be valuable, but it should fit within a financial plan that also supports the family raising that child.
Conclusion: A Head Start Worth Understanding
A Trump Account will not guarantee that a child becomes wealthy, nor will a $1,000 contribution eliminate the need for future saving and thoughtful financial decisions. Markets rise and fall, tax laws change, and actual results will differ from even the most carefully prepared illustration. The account’s importance lies less in promising a particular outcome and more in creating an unusually early starting point.
For eligible children born from 2025 through 2028, families have an opportunity to claim the federal contribution and introduce investing at the beginning of life. Additional contributions may strengthen the account, but its most valuable ingredient is present from the child’s first years: time.
Most adults eventually wish they had begun investing earlier. This generation may have the rare opportunity to begin before they are old enough to make that mistake.
Funds are mentioned for informational purposes only. References should not be considered a solicitation for the purchase or sale of securities or commodities.
Sources
U.S. Department of the Treasury, Treasury Announces Investment Lineup for Trump Accounts:
https://home.treasury.gov/news/press-releases/sb0551
Internal Revenue Service, Trump Accounts:
https://www.irs.gov/trumpaccounts
Internal Revenue Service, Working Families Tax Cuts, Trump Accounts:
https://www.irs.gov/newsroom/working-families-tax-cuts
Internal Revenue Service, Guidance on Trump Accounts and Contribution Rules:
https://www.irs.gov/newsroom/treasury-irs-issue-guidance-on-trump-accounts-established-under-the-working-families-tax-cuts-notice-announces-upcoming-regulations
Internal Revenue Service, Instructions for Form 4547:
https://www.irs.gov/instructions/i4547
Official Trump Accounts Website:
https://trumpaccounts.gov